Introduction - Vendor Credits
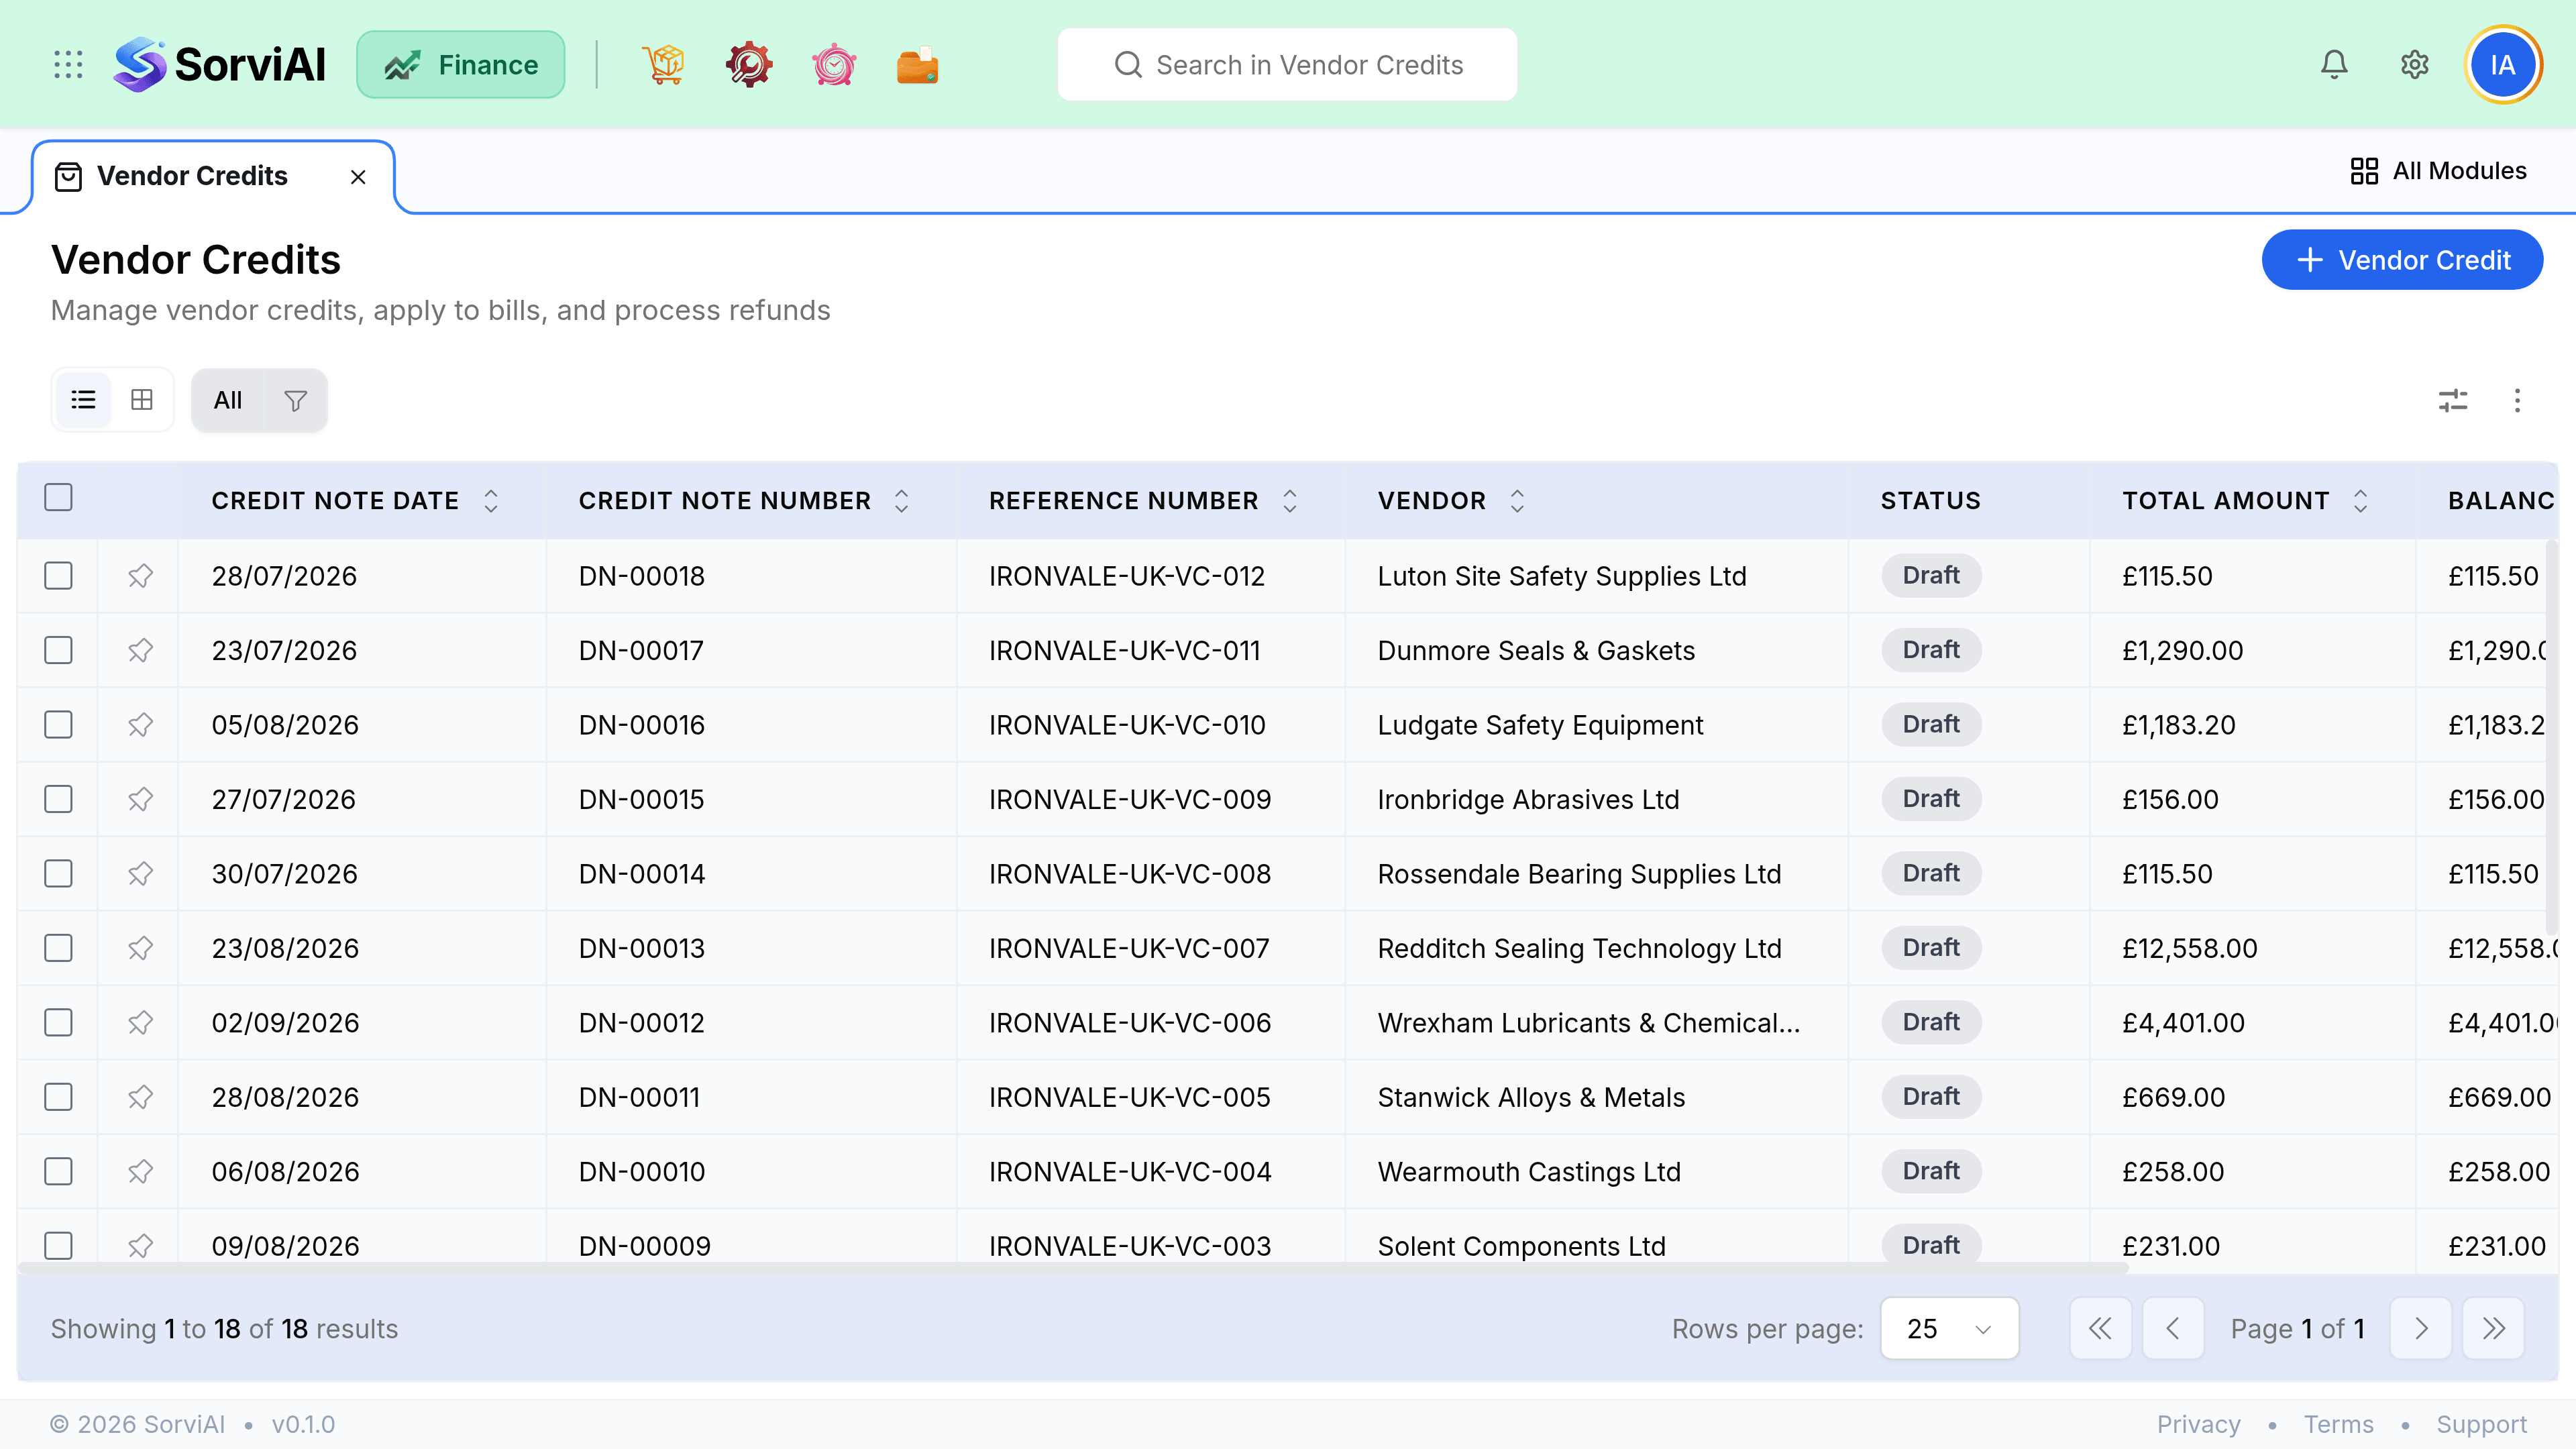
A vendor credit is a credit note received from a supplier.
It reduces what you owe them, and it is the purchase-side mirror of the credit notes you issue to customers. Overcharges, returned goods and agreed discounts all arrive as one.
What it is and is not
A vendor credit reduces the cash you send rather than arriving as cash itself. That is the useful thing to know about it, because it means an unused credit is money sitting idle until somebody applies it.
- Credit receivedVendor agrees a reduction
- RecordedAvailable balance on the vendor
- AppliedNext payment reduced
- Or refundedIf money comes back
Returned goods
If you sent physical goods back, the stock has to come out as well as the value. Record the stock movement in Inventory, then record the vendor credit for the value. The two are separate records because a supplier can credit you without wanting anything returned.