Introduction - Stock Adjustments
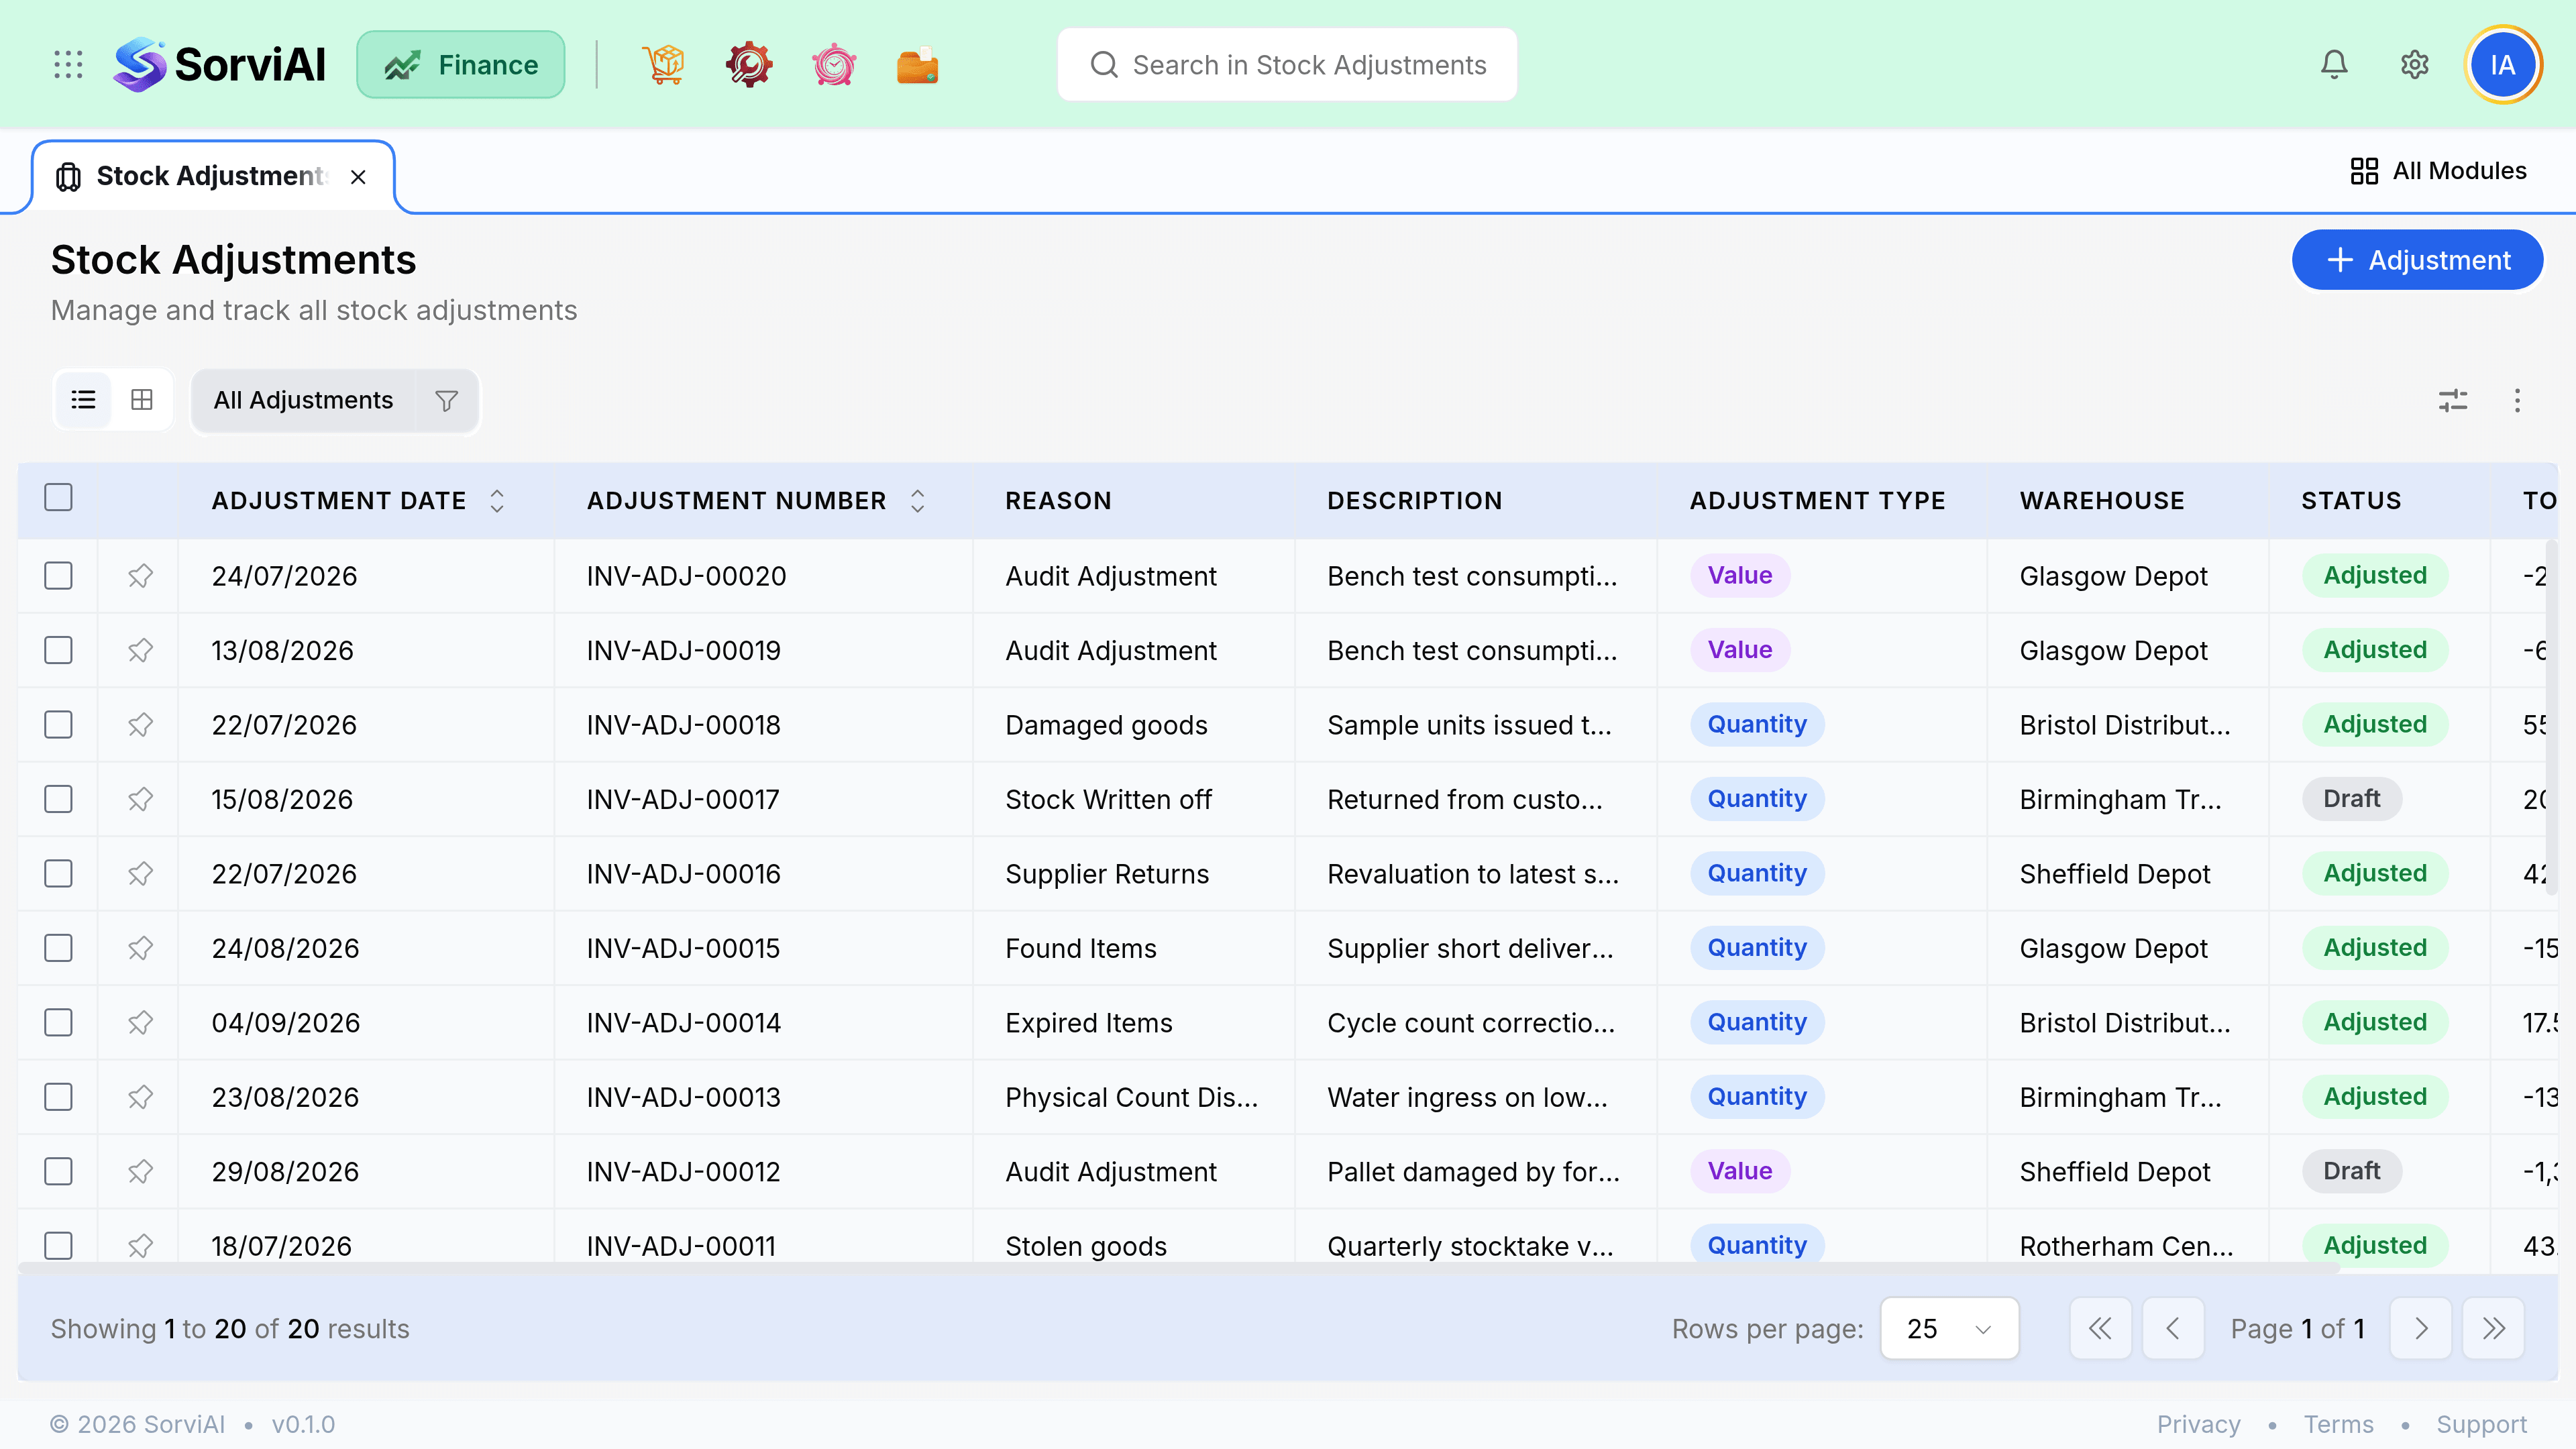
A stock adjustment changes quantity or value on hand without a sale or a purchase behind it.
It is the correction of last resort: the right tool for a stocktake difference, breakage or shrinkage, and the wrong tool for anything that has a proper document.
When to adjust
Before adjusting, check whether a real document should have moved the stock. An adjustment has no counterparty, so it explains nothing about where the goods went.
| Situation | Correct document |
|---|---|
| Stocktake found fewer units | Stock adjustment, shrinkage |
| Goods broke in the warehouse | Stock adjustment, damage |
| Goods arrived from a supplier | Purchase receive, not an adjustment |
| Goods went out to a customer | Shipment, not an adjustment |
| Goods moved between warehouses | Stock transfer, not an adjustment |
| Customer sent goods back | Return, not an adjustment |
Quantity or value
- Quantity adjustmentunits change
- You have more or fewer units than recorded. Value moves with the quantity at the item's current cost.
- Value adjustmentcost changes
- The unit count is right but what it is worth is not. Used for write-downs on obsolete or damaged stock that still physically exists.
The choice is made per adjustment, not per line, because mixing the two in one document makes the resulting journal entry impossible to read.
What an adjustment costs you
A write-off is a real cost hitting a real account, and unlike a sale it earns nothing. Adjustments are therefore worth watching as a number in their own right: the Stock Movement report filtered to adjustments is a good monthly read.
- An adjustment down posts the value to the account you choose, usually cost of goods or shrinkage.
- An adjustment up posts value into your stock asset from that same account.
- Neither touches revenue. There is no sale.
- Reason codes are what make the total explainable rather than embarrassing.