Other Actions in Journal Entries
Duplicating a repeat entry, attaching the working, and the monthly review that keeps journals from becoming the place mistakes go to hide.
Clone, or make a template
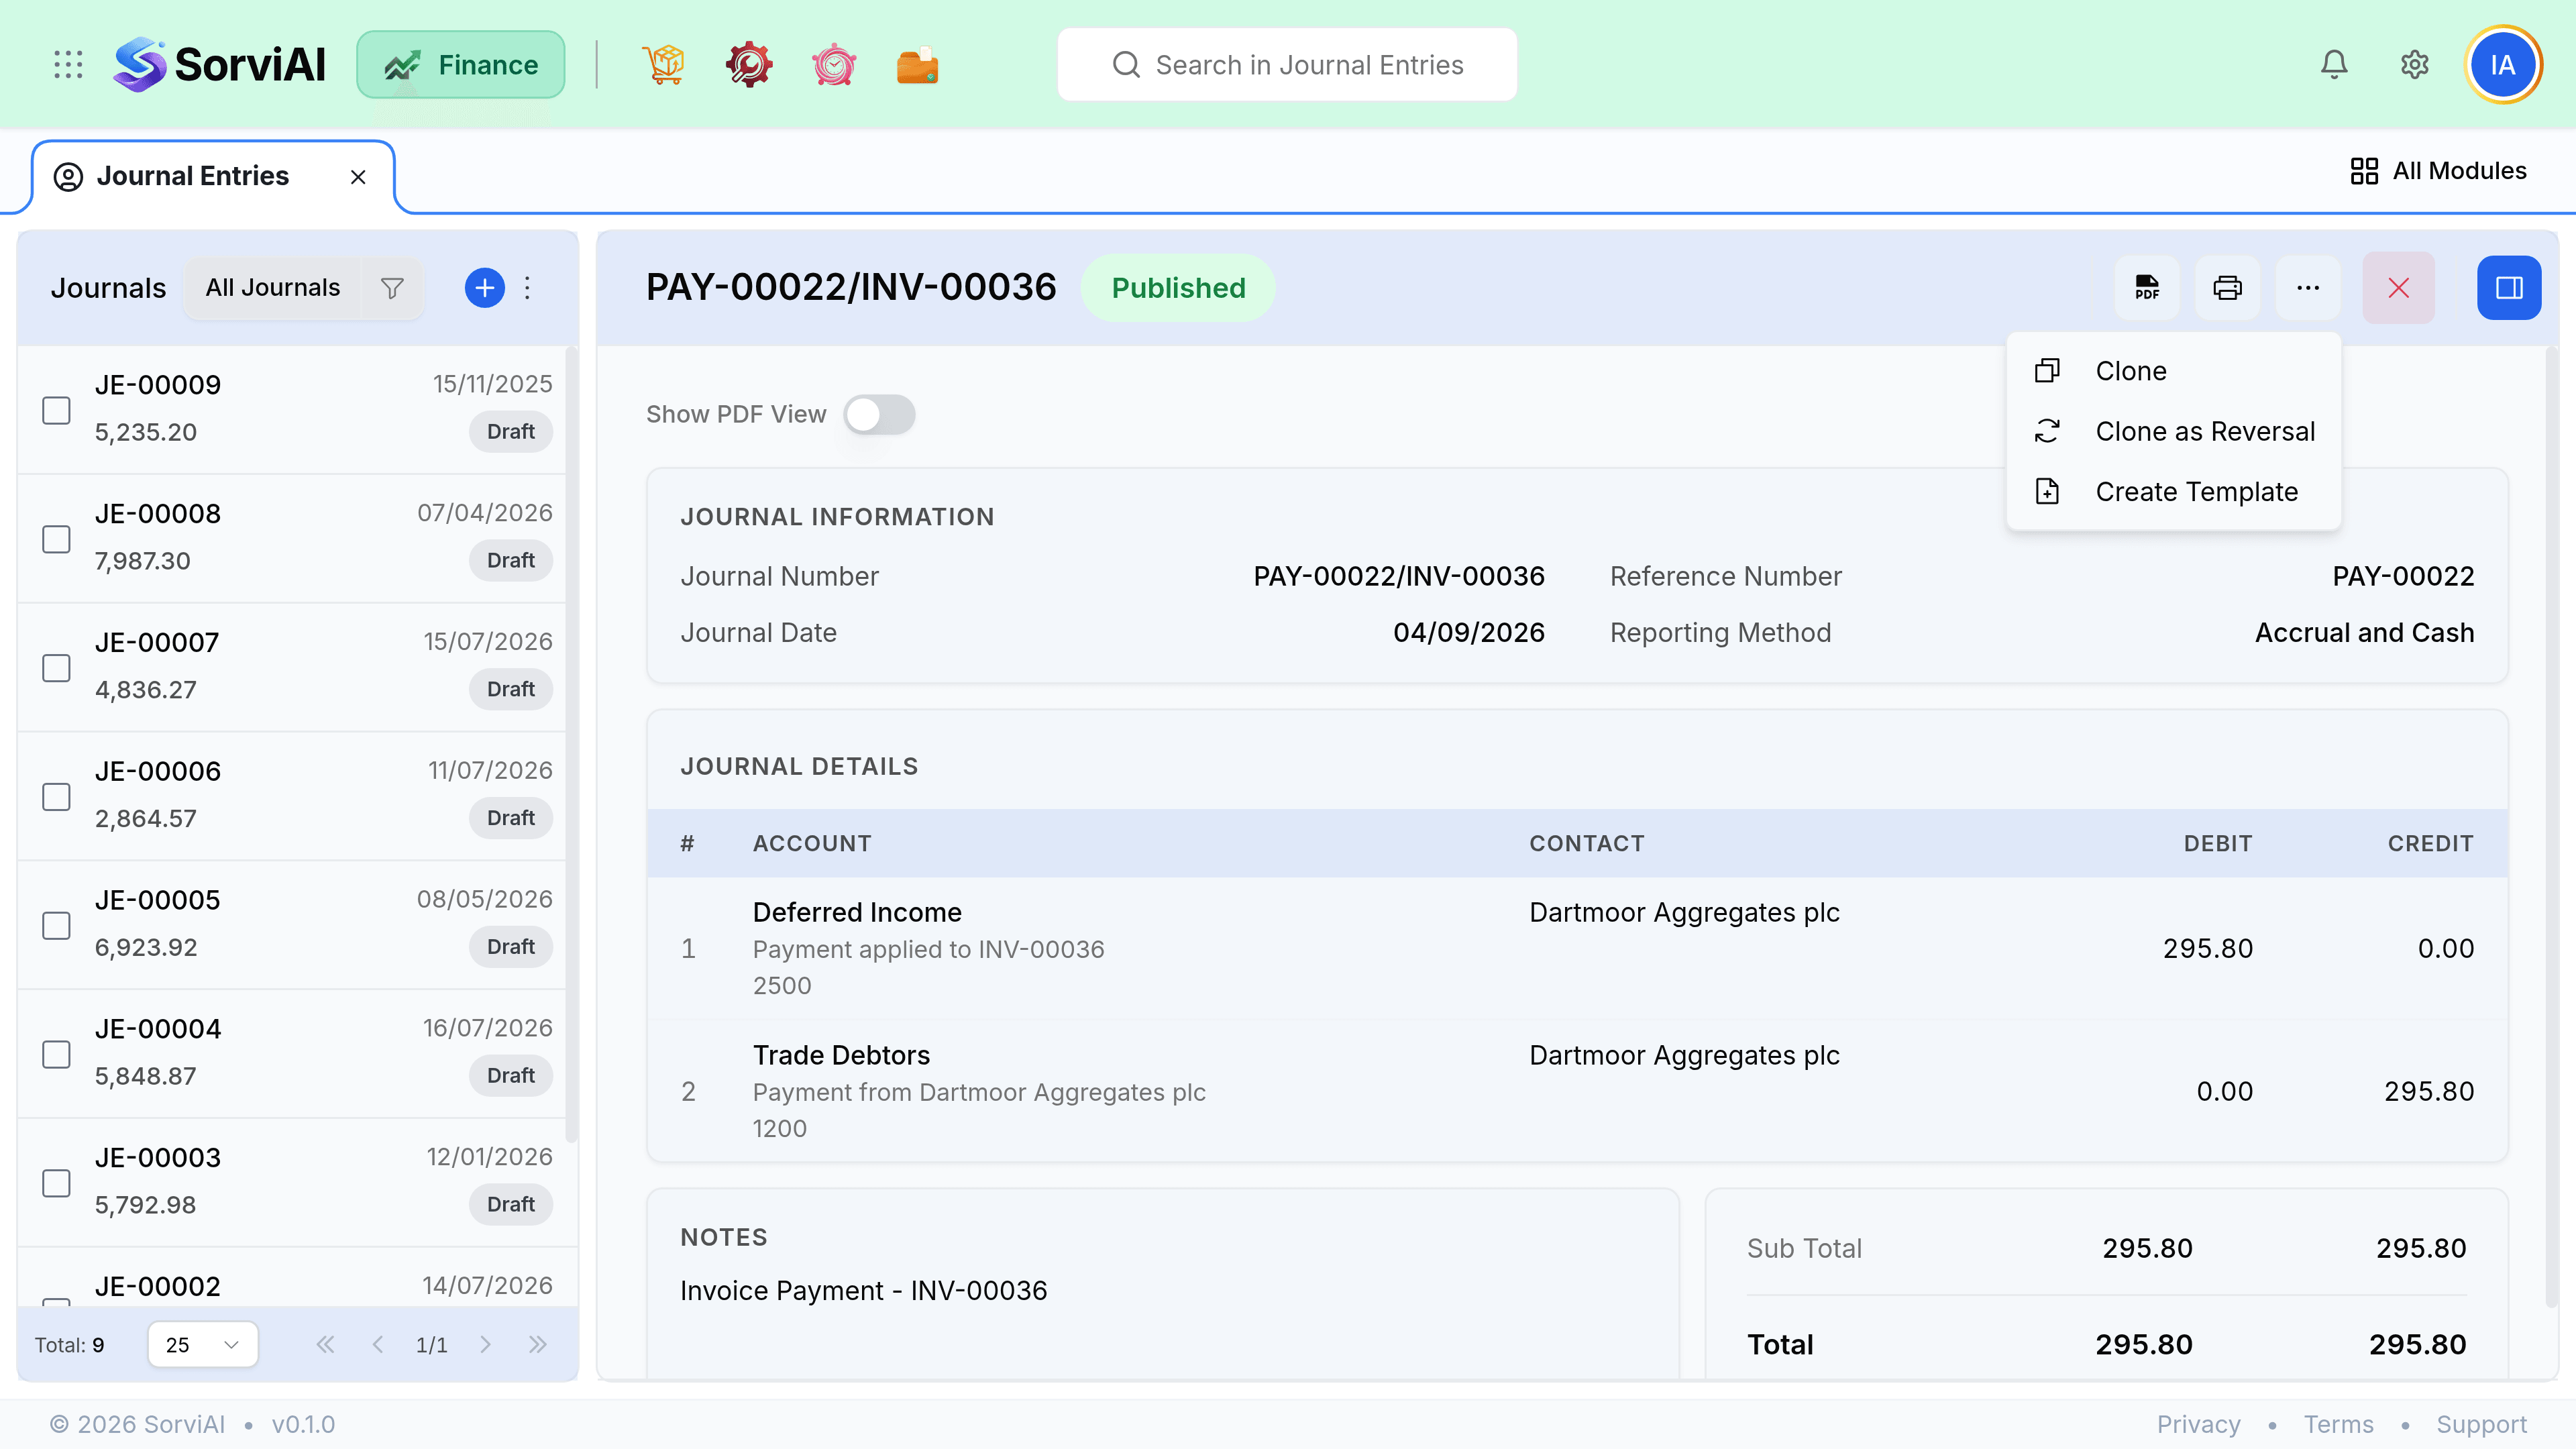
Depreciation, accruals and month-end reclassifications repeat with the same shape and often the same numbers. The overflow menu offers two ways to reuse one.
-
Clone copies last month's entry once: the lines, the accounts and the descriptions, and you change the date and the amounts.
-
Create Template turns the entry into something you draw from every month, which is the better answer for anything genuinely recurring.
-
Check the date. A clone defaults to today, which is rarely the period you want.
-
Check the amounts. Copying a depreciation figure is right; copying an accrual estimate usually is not.
-
Update the descriptions. "Accrue September electricity" in an October entry is worse than no description.
What cannot be deleted
| Entry | Deletable |
|---|---|
| Draft, or a posted manual journal | Yes. Deleting a posted one unwinds its effect on the account balances. |
| Void or reversed | No. Those states are the record of what happened. |
| Posted, generated by an invoice, bill or payment | No. Edit or delete the source document instead; the journal follows it. |
Attachments and evidence
A journal has no invoice behind it, so the attachment is the evidence. Anything an auditor would ask to see should be on the entry: the depreciation schedule, the accrual calculation, the email agreeing a write-off.
The monthly review
Filter journals to the period and read every one. It takes minutes and it is the single best control available in this module, because a journal is the only document in Finance that can post anything anywhere with no counterparty.
| What to look for | Why |
|---|---|
| Entries with no line descriptions | They will be unexplainable within a month. |
| Entries touching receivables or payables | They break the link to the ageing reports. |
| Round numbers with no attachment | Usually a plug rather than a calculation. |
| Accruals not reversed | The cost will be recognised twice. |
| Entries posted by someone unexpected | A permissions question worth asking. |